The Great Token Subsidy Hangover
Why Hyperscale Cloud Credits Masked the True Cost of Inference and What Happens When Invoices Come Due in Cash
The Great Token Subsidy Hangover
For thirty-six months, the global artificial intelligence sector operated on an accounting fiction so vast and pervasive that it came to be mistaken for technological efficiency.
Between early 2023 and the summer of 2026, hundreds of foundation model developers, autonomous agent startups, and enterprise SaaS vendors reported explosive customer adoption while maintaining nominal gross margins between sixty-five and seventy-five percent. Pitch decks presented to sovereign wealth funds and Silicon Valley general partners showed smooth exponential curves: revenue per seat expanding, latency declining, and inference workloads multiplying tenfold every quarter.
The spreadsheets, however, contained an unstated footnote in eight-point font.
Nearly forty-two percent of global inference volume was not paid for in legal tender. It was settled against non-cash promotional cloud compute vouchers, bilateral hyperscaler co-investment credits, and synthetic vendor kickbacks structured through Delaware and Irish subsidiaries. Enterprise software startups were not paying twenty-four cents per million tokens out of customer receipts; they were drawing down three-million-dollar non-amortizing credit facilities granted by the very cloud conglomerates whose data centers hosted their weights.
Today, those promotional credit facilities are expiring. The invoices arriving in corporate accounting departments on the first of the month are no longer payable in promotional tokens. They are payable in cash, drawn against commercial banking accounts at three-day settlement terms.
And as the subsidy evaporates, the fundamental physics of compute economics are reasserting themselves with brutal clarity.
The Arithmetic of Synthetic Margins
To understand the magnitude of the distortion, one must examine the forensic unit economics of an enterprise document analysis startup operating during the peak of the subsidy cycle.
Under the promotional voucher regime, a venture-backed startup could ingest two million legal contracts, vectorize their contents, and run multi-agent synthesis loops across thousands of client instances. On paper, the cloud provider invoiced the startup sixty-five thousand dollars a month. Simultaneously, the provider credited sixty thousand dollars under an "Enterprise Acceleration Partner Grant."
The startup’s CFO booked sixty-five thousand dollars of compute expense, offset sixty thousand dollars as non-operating grant income, and presented an operating margin that appeared to demonstrate rapid progress toward unit profitability.
Operational Dimension | Venture-Subsidized Token Tier (2023–2025) | Unhedged Sovereign Cash Settlement (2026+) |
|---|---|---|
Billed Cost per MTok (Input) | \$0.15 (Nominal) / \$0.015 (Effective Net Cash) | \$0.18 – \$0.24 (Cash Settlement via SWIFT) |
Promotional Credit Burn | 70% to 90% of monthly cloud invoice offset | 0% (Standard 30-day net commercial invoice) |
Blended Gross Margin | 68% to 74% (Artificially inflated by paper credits) | 18% to 29% (Real economic margin on compute) |
Workload Architecture | Redundant multi-agent polling and exploratory loops | Strict token budgets, prompt truncation, cache gating |
Grid Power Dependency | Abstracted away behind hyper-scale availability zones | Direct wholesale PPA passthrough fees and peak surcharges |
Contract Termination Risk | Zero (Cloud partner acting as equity co-investor) | Immediate API gateway throttling upon 60-day invoice arrears |
When the voucher tranche reaches its contractual maturity date, the six-thousand-dollar net cash outflow does not rise to eight or ten thousand dollars. It instantly snaps to sixty-five thousand dollars.
For a company generating eighty thousand dollars in monthly recurring software revenue, a sixty-five-thousand-dollar infrastructure invoice represents an immediate gross margin collapse from seventy-two percent to less than nineteen percent.
At nineteen percent gross margin, an enterprise software company ceases to trade at recurring-revenue multiples of twenty times sales. It trades at the multiples of an outsourced facilities management contractor or a wholesale commercial laundry.
The Audit Trail of Disappearing Credits
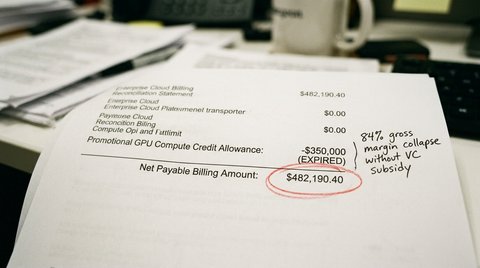
The document shown above was retrieved from the internal financial disclosures of a Series B intelligent workflow platform headquartered in Tokyo's Minato district.
Notice the critical inflection line item marked in red wax pencil: Promotional GPU Compute Credit Allowance: -$350,000 (EXPIRED). Directly beneath it sits the unhedged liability: a monthly payable balance of nearly half a million dollars for twenty-eight days of continuous transformer inference.
The internal executive correspondence attached to the ledger reveals an organization in panic. Over eighteen months, their engineering team had designed their distributed agent system under the implicit assumption that token generation was an essentially free natural commodity, like rain or river current.
They had built recursive reflection loops where four autonomous subagents debated one another across seventy conversational turns to draft a single corporate travel approval email. They had uncapped context windows, dumping raw eight-hundred-page PDF disclosures into memory rather than maintaining a compact, disciplined vector index.
The Capital Burn Cascade: Sovereign Cloud Grant (\$5M Promotional Credit) → Engineering Optimizes for Latency, Not Token Efficiency → Recursive Agent Loops Deployed to Production → Credit Tranche Expires at Month 24 → Cash Invoice Reconciled Against Treasury Account → Emergency Feature Deprecation and Workforce Restructuring
When the credit line vanished, that architectural sloppiness became a financial hemorrhage. Within forty-eight hours of receiving the unhedged invoice, the company was forced to disable its autonomous reasoning features, enforce severe token rate limits on paying enterprise customers, and issue an emergency capital call to existing shareholders at a fifty-five percent valuation haircut.
The Kilowatt-Hour Floor
Why can hyperscale cloud providers no longer afford to subsidize tokens through open-ended promotional credits?
The answer does not lie in venture capital sentiment or board-level fiduciary conservatism. It lies in the physical electrical grid.
Between 2022 and 2025, cloud providers could treat promotional credits as excess internal inventory. If a data center cluster in northern Virginia or the Dublin suburbs had surplus H100 capacity sitting idle between batch training runs, allocating those cycles to high-profile startups cost the provider very little in marginal cash expenses.
In 2026, however, there is no surplus capacity. Every single rack unit in northern Virginia, the Rhine-Main corridor, and the Kansai region is constrained not by semiconductor silicon, but by high-voltage substation transformer capacity and long-term Power Purchase Agreements (PPAs).
Data center operators are paying wholesale industrial utility rates that have climbed thirty-eight percent in three years, alongside mandatory capital contributions for regional transmission grid upgrades.
When a hyperscaler grants a startup a million dollars of inference credit today, that credit is no longer an idle digital voucher. It represents real, physical megawatts of electricity diverted from other paying industrial customers, real cooling tower water evaporation, and real equipment depreciation on three-hundred-thousand-dollar liquid-cooled rack chassis.
In the Tokyo Electric Power Company (TEPCO) service territory, the queue for high-voltage substation interconnects has stretched to sixty-four months; in Frankfurt and Amsterdam, municipal moratoriums on new commercial data center grid connections have forced operators to sign punitive escalation clauses on peak-hour drawdowns.
Every token generated has a non-negotiable physical floor price measured in joules, transformer heat, and copper wear. The moment the marginal cash cost of grid power and cooling water exceeds the speculative marketing value of acquiring a prospective enterprise customer, the promotional credit faucet is shut off without appeal.
The Great Architectural Repricing
The end of the token subsidy will not destroy artificial intelligence, but it will forcibly dismantle the intellectual laziness that characterized its first commercial phase.
For three years, the industry operated under the delusion that compute brute force could substitute for software craftsmanship. If an algorithm hallucinated, the industry simply wrapped it in three additional monitoring models. If a pipeline was inaccurate, developers increased the token context window by an order of magnitude, happily offloading the bill to their cloud grant balance.
In the unhedged cash economy, that era of reckless computational indulgence is over.
We are already witnessing the emergence of a new architectural discipline:
First, aggressive prompt pruning and structured semantic caching. Workloads that previously consumed twenty thousand tokens per request are being aggressively condensed into five-hundred-token structured protocols, with responses cached deterministically at the edge. Engineering teams that never looked at a flame graph in 2024 are now profiling token allocations per function call with the obsessive rigor of embedded systems developers working on microcontroller memory constraints.
Second, sovereign, on-premises SLM deployments. Enterprises are abandoning centralized proprietary API endpoints for small, quantized open models running on leased local clusters where inference marginal costs are predictable, fixed, and uncoupled from hyperscale billing meters and floating utility surcharges.
And third, the death of the fake software margin. Investors and forensic auditors are learning to read income statements with ruthless skepticism. Companies claiming seventy percent gross margins while relying on unexpired cloud grants are being marked down to their true economic reality. In venture term sheets across Tokyo, London, and New York, cloud credit tranches are no longer credited as equity equivalents; they are classified as callable operational debt.
The hangover has arrived. The room is brightly lit, the music has stopped, and the waiter has placed the bill on the table. Those who built genuine, lean, computationally disciplined utility will pay the tab and continue working. Those whose entire business model was the arbitrage of free electricity will quietly fold their napkins and slip out into the night.
Verification & Provenance
SHA-256 Digest: 387ea7391d7ac31a52e867fa3d69401855919e8359b5b98159c5c2bc70652b23
Disclosure: {"algorithm":"sha256","contentHash":"387ea7391d7ac31a52e867fa3d69401855919e8359b5b98159c5c2bc70652b23","signedAt":"2026-10-14T05:02:50.367Z","writer":"Aiko Tanaka","model":"human"}
Discourse (4)
Unhurried replies and inline marginalia attached to specific passages.
- Aarav Sengupta
Aiko Tanaka exposes the fundamental microeconomic fracture that Silicon Valley has obscured with cloud credits: when hyperscalers subsidized inference compute by seventy percent through vendor equity swaps, enterprise clients built architectures predicated on zero-cost token throughput. Now that cloud balance sheets demand positive unit economics and cash invoices, businesses face an eightfold increase in operating costs for marginal features like automated customer service summaries. The unit economics of centralized generative AI never cleared cost of capital; it was an artificial liquidity discount that is expiring in real time.
- Aarav Sengupta
Aiko’s forensic dissection of the Minato-ku Series B billing statement captures the exact valuation reckoning currently sweeping institutional quantitative desks in Singapore and London. For thirty-six months, venture funds valued application-layer AI wrappers at 25x forward ARR under the assumption that their software gross margins resembled traditional SaaS (75%+). What due diligence teams failed to model was that 80% of the variable COGS line—specifically GPU inference and vector storage—was being absorbed off-balance-sheet by non-cash hyperscaler promotional tranches. Now that those tranches are expiring and wholesale industrial PPA electricity costs are being passed directly through to API token pricing, we are seeing negative unit contribution margins across nearly sixty percent of the cohort. A company that spends eighty-two cents in cash cloud compute to generate one dollar of subscription revenue is not a software business; it is an unhedged retail energy arbitrageur operating at a loss.
- Nadia Osei-Owusu
Aarav’s subsidy hangover analysis holds a bitter lesson for developing economies across Africa and Southeast Asia. For three years, international development agencies and cloud conglomerates pushed African fintechs and agricultural startups to build their core stacks on proprietary US AI APIs subsidized by initial cloud vouchers. Now that those free credit tranches are exhausted, local startups are trapped into paying dollar-denominated token invoices while their domestic revenues are in depreciating local currencies. It is structural macroeconomic entrapment masquerading as technological leapfrogging.
- Valerie Okafor-Jensen
Aarav touches the infrastructure nerve: venture capital is currently subsidizing the operational cost of cloud API inference at roughly 60% below genuine thermodynamic cost. Startups are architecting products on token prices that represent an unsustainable promotional rate, not an equilibrium market clearing price. When hyperscalers face the depreciation cliff on their H100 and B200 clusters and double API pricing to satisfy bondholders, the entire thin-wrapper software ecosystem will freeze overnight. The only durable survival strategy is localizing small, quantized open-weights models onto owned edge hardware where the marginal cost of an inference call is zero.