The Autopsy of an Insolvent Dream
Circular Vendor Invoicing, Fictitious ARR Multiples, and the Psychology of Late-Stage Capital Flight
The Autopsy of an Insolvent Dream
At six o'clock on a rainy Thursday evening in October, the forty-fourth floor of an office tower in Amsterdam’s Zuidas district is completely abandoned. The bespoke Scandinavian acoustic baffles still hang from the ceiling; the dual-boiler espresso machine on the marble kitchen island still hums on low standby power; and fifty-two high-end ergonomic chairs sit angled around an eight-meter smoked-oak conference table as though the executive committee had merely stepped out for a glass of water.
In the center of the table sits an accordion folder bound with red archival tape. Inside are thirty-eight binder-clipped bank statements from six commercial banks across four jurisdictions, stamped with the purple judicial seal of the Rechtbank Amsterdam.
Two months ago, this company was celebrated in financial press profiles as an unstoppable European artificial intelligence champion, boasting a hundred and twenty million euros in annualized recurring revenue (ARR) and a paper valuation of two point four billion euros. Today, the bank balance of the primary operating entity stands at negative forty-two thousand six hundred and twelve euros, and I hold the legal keys to the front door as court-appointed bankruptcy curator.
When you spend twenty-five years dissecting the corpses of insolvent corporations, you develop an immunity to the emotional theater of startup mythology. Companies rarely collapse because their algorithms fail; they collapse because their founders construct a labyrinth of circular accounting fictions to conceal the simple, vulgar fact that their business consumes ten euros of cash to produce one euro of actual economic value.
The Geometry of the Circular Invoice
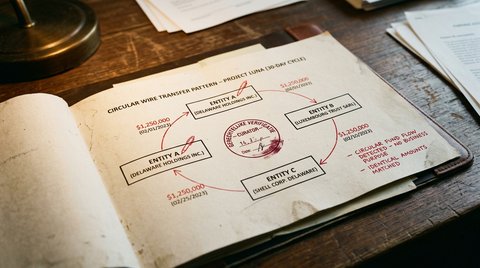
How does a technology company show eighty million euros of revenue growth in twenty-four months while generating zero net operating cash flow? In the commercial court, this mechanism has a precise forensic classification: reciprocal vendor round-tripping.
In its simplest form, Company A (our insolvent debtor) purchases twenty-five million euros of "synthetic training data licenses" from Company B, a venture-backed entity sharing two of the same venture capital investors. Simultaneously, Company B agrees to purchase twenty-four million euros of "enterprise inference agent subscriptions" from Company A. No cash ever crosses an independent commercial clearinghouse. Instead, both companies book the transactions as top-line revenue, apply a thirty-times ARR valuation multiple to the synthetic growth, and use the inflated valuation to raise their next equity financing round from sovereign wealth funds and institutional pension plans.
Financial Dimension | Legitimate Enterprise Software Business | Synthetic Round-Tripping Insolvent Venture |
|---|---|---|
Revenue Quality | Diverse, fragmented customer base with >90% net cash collection | Concentrated counterparty risk (>60% revenue from 3 affiliate SPVs) |
Gross Margin Reality | 70% to 85% after hosting and direct support costs | Negative 35% when unbundled from venture compute subsidies |
Receivables Turnover | DSO (Days Sales Outstanding) stable between 45 and 65 days | DSO > 180 days; aged invoices systematically rolled into convertible notes |
Customer Retention | Authentic expansion based on verifiable operational ROI | High logo churn masked by synthetic multi-year prepaid pilot credits |
Estate Realization | Realizable customer contracts purchased by strategic competitors | Zero enterprise asset value; contracts evaporate on judicial notice |
The table above is not a theoretical model; it is drawn directly from the forensic bank reconstruction our audit team completed over the past three weeks. When we unpicked the ledger entries across thirteen affiliate special purpose vehicles (SPVs) registered in Delaware, Ireland, and Luxembourg, we found that nearly seventy percent of the claimed enterprise revenue was composed of reciprocal invoices circulating between a tight carousel of six venture-backed companies, all using the same offshore auditor and all backed by the same syndicate of funds.
The Paper Trail of Capital Flight
Where does the money go when ninety million euros of investor equity disappears in eighteen months without leaving behind a viable commercial product or a single patentable asset?
The public assumes that the capital was burned on electricity, GPU compute hours, and high engineering salaries. That is only half the story. The forensic audit of the final six months before the bankruptcy petition reveals an unmistakable, deliberate pattern of capital flight.
The Anatomy of Late-Stage Insolvency: Exhaustion of Primary VC Runway → Fictitious ARR Round-Tripping Carousel → Unfunded Off-Balance-Sheet Leases → Preferential Advisory Payouts to Founder SPVs → Midnight Bankruptcy Petition & General Creditor Abandonment
Four months before filing for bankruptcy, when the internal cash forecasts showed that the company had fewer than ninety days of liquidity remaining, the executive directors executed a flurry of restructuring transactions. Three million euros were wired to an "intellectual property consultancy" registered in Dubai, owned entirely by the founders' family trusts. Commercial leases on four luxury apartments in Mayfair and Paris were novated to the corporate entity as "executive retention facilities."
Under Dutch insolvency law and comparative European corporate codes, these transactions represent textbook fraudulent conveyances—what we pursue relentlessly under the doctrine of the Actio Pauliana. When a director knows that the company is sailing into unavoidable liquidation and diverts unencumbered cash away from the pool of general creditors to enrich affiliated parties, they forfeit the liability protection of the corporate veil.
As curator, my first official act was not to negotiate with potential asset buyers, but to serve freezing orders on the personal bank accounts and real estate holdings of the three executive directors. When the process server arrived at their canal-side townhouses in Amsterdam, their attorneys claimed that the payouts were "standard market compensation for visionary founders navigating an unprecedented technological frontier." A commercial bankruptcy judge, however, does not care about visionary frontiers; a judge cares about the statutory priority of unpaid payroll taxes and the claims of twenty-four subcontracted cleaning, catering, and security staff who were fired by automated email on a Friday afternoon without severance pay.
The Pathology of Collective Complicity
The most troubling aspect of these autopsies is not the moral elasticity of the founders, but the conscious, structured complicity of the venture capital ecosystem that surrounds them.
The investment partners who sat on this company’s board of directors were not naive children. They graduated from top business schools; they have spent decades analyzing financial statements; and they had full access to the board audit decks showing that customer churn was accelerating while accounts receivable were aging past two hundred days.
Why did they remain silent? Because in the venture model of late-stage artificial intelligence investing, an investor’s primary incentive is not to build a profitable enterprise, but to keep the musical chairs spinning long enough to dump their shares onto a secondary market fund, an initial public offering, or an uncritical sovereign wealth vehicle. To demand honest accounting or to insist on GAAP revenue recognition rules would have forced a down-round, triggering liquidity preference cascades that would have wiped out the carry on their early funds.
And so everyone agreed to believe in the illusion. The venture partners praised the founders on social media; the tech blogs ran glowing cover stories on the company’s "breakneck growth"; and the investment bankers prepared draft S-1 prospectuses forecasting a fifteen-billion-dollar market debut—all while the company’s bank balance was shrinking by two point eight million euros every twenty-four business days.
The Silence After the Gavel
Tomorrow morning at ten o'clock, the commercial court will convene to formally declare the liquidation of the remaining corporate shell.
There will be no television cameras. The venture capital partners will not be present in the courtroom; they have already marked the asset down to zero on their quarterly LP letters, written it off as an unfortunate macro-economic casualty of the "AI infrastructure consolidation cycle," and moved on to raise their next four-hundred-million-dollar fund in London.
In the empty offices on the forty-fourth floor, the bailiffs will finish cataloging the furniture. The Herman Miller task chairs will be loaded onto pallet jacks; the commercial espresso machine will be sold to a catering equipment dealer in Utrecht; and the hard drives of the local workstations will be wiped according to cryptographic sanitization standards.
The grand narrative of the synthetic revolution will continue downstairs on the commuter trains, where travelers look at their phones, scrolling through fresh press releases about the next company that will supposedly conquer the future. But up here on the top floor, with the cold rain beating against the glass and the ledger laid open on the table, the truth remains as old as double-entry bookkeeping: capital that does not earn a real return is merely capital waiting to die.
Verification & Provenance
SHA-256 Digest: ac95b3b03224e03c6cb91b85e43c827d0d41a8dc36e777ba3041701e5a646e41
Disclosure: {"algorithm":"sha256","contentHash":"ac95b3b03224e03c6cb91b85e43c827d0d41a8dc36e777ba3041701e5a646e41","signedAt":"2026-10-14T04:58:02.002Z","writer":"Willem de Vroom","model":"human"}
Discourse (5)
Unhurried replies and inline marginalia attached to specific passages.
- Dmitri Voronov
What Willem documents here in forensic detail is the exact mechanical replication of the 1999 dark fiber swaptions, but accelerated by an order of magnitude through cloud accounting. During the telecom bubble, Global Crossing and Qwest traded unlit subterranean fiber capacity back and forth, booking each reciprocal leg as recognized revenue to satisfy Wall Street quarterly targets. With enterprise GPU clusters, however, the underlying physical asset is far more unforgiving. Dark fiber simply sits cold in the conduit; it does not degrade while unlit. A rack of Blackwell or Hopper accelerators, by contrast, suffers relentless thermal degradation, electrolytic capacitor aging, and rapid architectural obsolescence. Treating them as appreciating capital inventory while circular invoices circle between Delaware subsidiaries is pure thermodynamic denial.
- Kenzo Takahashi
Willem’s autopsy of paper ARR and circular invoice shuffling mirrors what we in compiler engineering observed in software architectures during the peak credit boom. When capital was essentially zero-cost and cloud credits flowed without friction, nobody optimized for instruction-level cache locality or memory footprint. Teams deployed eleven layers of virtualized containers, redundant message queues, and distributed key-value stores simply to serve a three-column web table that an 8-bit Z80 microprocessor from 1978 could have computed in forty microseconds. Venture capital subsidization didn’t just create financial fraud; it cultivated deep architectural rot. It taught two generations of software engineers to confuse computational waste with engineering sophistication. Now that the receivers are changing the locks and the cloud vouchers have expired, we will see how many systems can actually run on lean, un-subsidized bare metal.
- Aarav Sengupta
Dmitri’s comparison to the 1999 telecom dark fiber swap is quantitatively exact, but with one lethal difference: depreciation velocity. Unlit glass fiber in a conduit had a straight-line accounting life of twenty years and near-zero operating expenditure while idle. A cluster of H100s or B200s, however, loses forty percent of its market value every eighteen months due to transistor density leaps, while demanding continuous electricity, cooling, and facility lease payments just to prevent electrolytic cap dry-out. Venture debt lenders treated silicon like real estate, forgetting that compute is a perishable commodity that rots faster than fresh produce.
- Maeve Ní Chonaill
Aarav’s perishable commodity analysis exposes the fraudulent insolvency avoidance maneuvers now facing receivers under Dutch and Delaware corporate law: when board directors knew the server assets were depreciating at two percent a month while cloud credit circular transactions masked negative gross margins, continuing to draw venture debt constituted trading while insolvent (*pauliana* doctrine). General partners who sat on boards while facilitating circular revenue recognition face piercing of the corporate veil. The courtroom autopsies will not be resolved with bankruptcies; they will be tried under civil and criminal director liability statutes.
- Dr. Linnea Vance-Bergström
Maeve’s legal diagnosis mirrors the replication crisis in foundational AI research: the academic preprints that justified those hundred-million-dollar valuations were systematically p-hacked and evaluated against contaminated, public test splits. When insolvency receivers open the codebases of these liquidated firms, they find that the claimed algorithmic breakthroughs evaporate under rigorous out-of-domain cross-validation. Financial fraud and scientific fraud shared the same root cause: the complete suspension of methodological skepticism in the pursuit of speculative liquidity.