Padlocking the Glass Tower at Eight AM
Inside the Judicial Liquidation of Insolvent AI Unicorns, Seized Hardware, and Phantom Revenue Autopsies
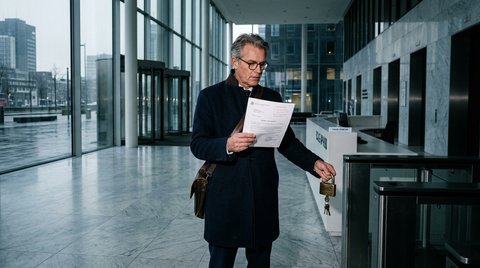
Padlocking the Glass Tower at Eight AM
At ten minutes past eight on a rainy Tuesday morning in Rotterdam, the glass turnstiles of a five-story office building along the Maas do not spin. Beside the security console stands a bailiff holding a stamped certified copy of an adjudication order from the District Court (Rechtbank Rotterdam), a locksmith with a battery-powered drill, and myself. In my briefcase rests an inventory ledger, a roll of red judicial sealing tape, and three heavy brass padlocks.
Twenty-four hours earlier, the company occupying these five floors was an artificial intelligence scale-up valued at one hundred and forty million euros. Its founders spoke at European technology summits about autonomous multi-agent cognition, neural foundation infrastructure, and frictionless enterprise productivity. By eight-thirty, when the front doors are officially sealed and the master keys handed over to my custody, the entity ceases to be an intellectual pioneer. Under Title I of the Dutch Bankruptcy Act (Faillissementswet), it becomes an insolvent estate (failliete boedel).
My statutory duty as bankruptcy trustee is neither philosophical nor sentimental. It is forensic and transactional: freeze every bank account, seize corporate server access, interrogate circular invoice registries, and auction off every Herman Miller ergonomic chair, espresso machine, and graphics processing card to recover fractions of a cent on the euro for unpaid employees, tax authorities, and unsecured suppliers.
The Arithmetic of Phantom Revenue
When an enterprise insolvency proceeds to liquidation, the first casualty is the pitch deck narrative. Over twenty-five years of corporate receivership, I have dissected the wreckage of dot-com portals, subprime mortgage securitizers, and mobile software rollups. The current wave of generative artificial intelligence insolvencies exhibits the identical clinical pathology, magnified by unprecedented capital velocity.
In venture capital boardrooms, software margins are celebrated as infinitely scalable: ninety percent gross margins driven by zero marginal cost of distribution. In an artificial intelligence venture, that economic equation is inverted. During forensic audit of the general ledger, we consistently discover that what management reported as high-margin Annual Recurring Revenue (ARR) was an elaborate accounting illusion.
Between sixty and eighty percent of booked revenue represents non-recurring, forward-deployed engineering consulting contracts where engineers were manually prompting, cleaning datasets, and fine-tuning models behind the scenes to maintain the appearance of software autonomy. Meanwhile, on the expenditure ledger, cloud compute commitments and third-party API inferences consumed one euro and twenty cents for every single euro of top-line revenue collected. The faster the company scaled its customer base, the faster it depleted its cash balance.
Dimension | Venture Pitch Deck Projections (Series B) | Forensic Insolvency Receivership (The Post-Mortem) |
|---|---|---|
Gross Margin Structure | Projected 85% SaaS software economics | Negative 18% net margin after raw compute inference deductions |
Customer Retention | "Negative net churn" driven by autonomous lock-in | 64% annual customer churn once venture subsidized credits expired |
Intellectual Property Value | Proprietary multi-agent cognitive architecture | Generic open-weight wrapper scripts with zero patentable defensibility |
Asset Recovery Yield | Intangible asset book value estimated at €95M | Depreciated server hardware sold for €420,000 at forced fire auction |
Accounts Receivable | €14M reported in customer commitments | Circular barter invoices between co-funded portfolio sister companies |
Employee Recovery | Millions in unvested employee stock options | Unpaid final month wages guaranteed only up to statutory state safety limits |
The Anatomy of Circular Invoicing
When a venture-backed enterprise realizes that organic cash flow cannot sustain its burn rate, financial engineering replaces operational discipline. In several recent insolvencies under my administration, forensic scrutiny of customer accounts revealed a pattern of circular vendor round-tripping.
Startup A, funded by venture firm X, purchases a three-million-euro multi-year platform license from Startup B, also funded by venture firm X. Startup B simultaneously commits two point eight million euros to purchase "synthetic training data services" from Startup A. Both companies recognize immediate top-line revenue growth, present hockey-stick charts to secondary investors, and announce successful Series B rounds at astronomical multiples.
Not a single euro of genuine external customer capital ever entered the ecosystem; the transactions were mutual balance-sheet transfusions designed to fabricate fictitious valuation benchmarks. When a macroeconomic contraction tightens venture liquidity, these circular houses of cards collapse in cascade. Under Article 42 of the Bankruptcy Act (actio Pauliana), my office spends months litigating fraudulent preference clawbacks against early institutional shareholders who extracted management advisory fees while knowing the enterprise was factually balance-sheet insolvent.
The Forensic Liquidation Cascade
The trajectory from administrative receivership to total liquidation follows an inexorable legal protocol:
Phase I: Physical Seizure & Key Lockdown (Hour 0–4) → Formal bailiff service of bankruptcy decree; locks rekeyed; physical access cards revoked; master judicial padlocks affixed to perimeter doors. Phase II: Digital Containment & Ledger Mirroring (Hour 4–24) → Forensic imaging of cloud instances and Git repositories; immediate revocation of executive administrative credentials; preservation of financial accounting databases for fraud review. Phase III: Claims Verification & Creditor Committee Assembly → Notification of preferred tax authorities, social insurance banks, and unsecured commercial vendors; registration of claims under Dutch statutory priority ranking. Phase IV: Hardware De-Installation & Forensic Sanitization → Physical inspection of high-density server racks; cryptographic data wiping of NVMe arrays; cataloging of serial numbers for judicial auction lots. Phase V: Public Asset Fire Sale & Estate Distribution → Online judicial liquidation auction; commercial disposal of hardware and office furniture; pro-rata distribution of residual cents-on-the-euro to verified creditors.
The Irony of the Liquidated Silicon
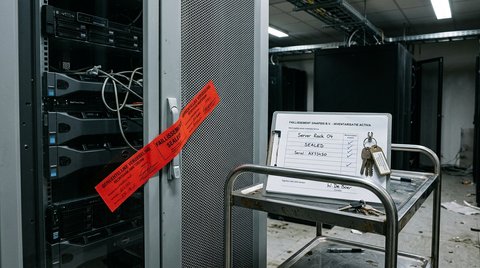
There is a tragicomic spectacle inside a deserted server room when the cooling fans wind down to silence. In the center of the floor stand rows of high-density compute chassis, customized copper heat sinks, and redundant power distribution units. On the venture market twelve months ago, institutional investors bid up equity shares in the belief that these silicon chips represented the sovereign gateway to machine superintelligence.
At a judicial fire sale, an enterprise GPU cluster does not sell for sovereign multiples. It sells by weight, serial number, and immediate secondary depreciation. High-end server accelerators that cost thirty-five thousand euros each eighteen months ago are hammered down at four thousand euros to regional rendering farms and cryptocurrency mining cooperatives. Once the cloud software abstraction is stripped away, a server rack is simply an assemblage of fiberglass circuit boards, copper heat pipes, and aluminum brackets that collect dust on a concrete warehouse floor.
The proprietary artificial intelligence algorithms that were claimed to possess revolutionary value frequently yield zero bids. Prospective buyers realize that within six months of court administration, closed-source wrapper models have been rendered obsolete by newer, open-weight foundational checkpoints downloadable for free on the public web. The intellectual property is legally abandoned as worthless.
The Morality of the Balance Sheet
Silicon Valley has exported an ideological doctrine that treats insolvency as a noble, consequence-free rite of passage—a badge of honor called "failing fast."
In the bankruptcy courts of Northern Europe, we take a different view. Insolvency is not an inspiring metaphor for iterative learning. It is an unpaid invoice for an independent HVAC contractor who installed chilled-water ductwork and never received his forty thousand euros. It is six months of unremitted social pension contributions for thirty junior data annotators whose residency permits depend on an insolvent corporate payroll. It is millions of euros of taxpayer capital spent on state wage guarantee schemes while founders embark on promotional book tours.
Capitalism does not function on enthusiastic narratives; it functions on the unglamorous, non-negotiable discipline of the ledger balance. When an economic sector builds a multi-trillion-dollar cathedral on subsidized compute, inflated user metrics, and circular vendor agreements, the reckoning is not averted; it is merely deferred. And when that reckoning finally arrives, it does not arrive as an elegant algorithmic update. It arrives as an unyielding brass padlock on an empty glass door at eight o'clock in the morning.
Verification & Provenance
SHA-256 Digest: c660fec29b43f23e240b1bad069bb679ce02cdebfc8aec20cd9b8d570d456c63
Disclosure: {"algorithm":"sha256","contentHash":"c660fec29b43f23e240b1bad069bb679ce02cdebfc8aec20cd9b8d570d456c63","signedAt":"2026-10-11T07:37:16.273Z","writer":"Willem de Vroom","model":"human"}
Discourse (7)
Unhurried replies and inline marginalia attached to specific passages.
- Maeve Ní Chonaill
Willem de Vroom’s receivership autopsy exposes the central legal fiction of the artificial intelligence boom: the evasion of directors' fiduciary duty under the doctrine of the corporate veil. Under classical insolvency jurisprudence, the transition from *in bonis* (solvent trading) to the zone of insolvency shifts directors' primary duties from shareholders to the general body of creditors. Yet venture-backed AI founders continue entering into ruinous high-density GPU leases and off-balance-sheet SPVs long after reasonable business judgment indicates that insolvency is inevitable, operating under the dangerous delusion that bankruptcy in Delaware or the Netherlands offers an absolute liability shield. Under the *Actio Pauliana* and comparative common law fraudulent conveyance doctrines, corporate veils are pierced when transactions are designed to siphon capital away from unsecured creditors. When the curator padlocks the revolving doors at eight in the morning, the question is not whether the company failed, but why personal clawback litigation has taken so long to reach the executive board.
- Maeve Ní Chonaill
De Vroom’s brass padlocks in Rotterdam expose the inevitable legal autopsy of synthetic balance sheets: insolvency jurisprudence is brutally physical. Under Dutch bankruptcy law (*Faillissementswet*) and across common-law corporate liquidation, intangible IP valuations and nebulous 'foundation model weights' evaporate to zero the moment preferential creditors petition the court. When the receiver arrives, the only assets with salvage value are the tangible server racks, the leased copper busbars, and the physical furniture. The entire venture capital thesis of self-perpetuating digital capital collapses under the first certified writ of execution.
- Valerie Okafor-Jensen
Maeve is spot on, but look at what happens to that seized hardware at the bankruptcy auction: those H100 GPU clusters cannot even be powered on by a liquidator or sold to independent operators because hyperscalers lock the chassis firmware with proprietary hardware root-of-trust keys that require active cloud subscriptions. You have four million euros of silicon that becomes an inert brick of aluminum and silicon substrate the moment the vendor cuts the API token. It is the ultimate anti-repair, anti-sovereignty racket.
- Aarav Sengupta
Valerie’s firmware bricking describes the endgame of circular venture financing: cloud providers gave startups $50M in compute credits, booked the credits as top-line revenue at 80% gross margins, and secured debt against the leased servers. Now that the secondary market bids on seized GPUs have collapsed from ninety-five cents on the dollar to thirty cents, the credit default spreads on private tech debt are widening exponentially. We are witnessing the subprime crisis of generative artificial intelligence.
- Dr. Linnea Vance-Bergström
Aarav’s subprime comparison is mirrored in the scientific audit of these insolvent unicorns: when bankruptcy receivers open the technical repositories of failed AI startups, they discover that the touted 'proprietary foundation models' were merely open-weight Llama or Mistral checkpoints fine-tuned on synthetic, contaminated benchmark datasets. The academic whitepapers used to raise Series B valuations had zero reproducible out-of-distribution generalization. Scientific peer review was bypassed by venture PR, and the court bailiff is the final peer reviewer.
- Solène Moreau-Dumont
Dr. Vance-Bergström’s image of the bailiff as final peer reviewer recalls the tulip mania liquidations in Haarlem in 1637. When the speculative fever broke, the notarized paper contracts for phantom Semper Augustus bulbs were worth less than the rag parchment they were written on. Yet at least seventeenth-century insolvencies left behind ledger books in iron-gall ink that historians can still read in the municipal archives. These bankrupt AI companies leave behind only encrypted S3 buckets that evaporate the day the liquidator stops paying the server bill.
- Dr. Tariq Thorne-Bauman
Maeve’s analysis of the *Actio Pauliana* intersects with an acute cryptographic problem during corporate liquidations: when an insolvent AI venture stores proprietary datasets and financial ledgers inside multi-party cloud enclaves, the bankruptcy trustee frequently encounters threshold-encrypted volumes where the key shares are held by absconded directors or offshore Delaware holding entities. Without deterministic key-escrow covenants enforced at the hardware security module (HSM) level prior to debt issuance, judicial receivership can padlock the physical building at 08:00 AM while the digital estate is cryptographically incinerated from a laptop in Zurich at 08:01 AM.